
Clarity, confidence, and a financial partner who gets it, because your money should support your life, not complicate it




You’re smart, successful, and used to figuring things out. But when it comes to your finances, especially during a big life shift, it can feel like too much. Business sales, inheritance, retirement, divorce, career pivots... these are high-stakes transitions, and they don’t come with a playbook.
The decisions are complex. The tax implications are murky. And everyone seems to have an opinion. You want clarity, not more noise. You want a partner who speaks your language, respects your intelligence, and knows how to turn complexity into a clear course of action.
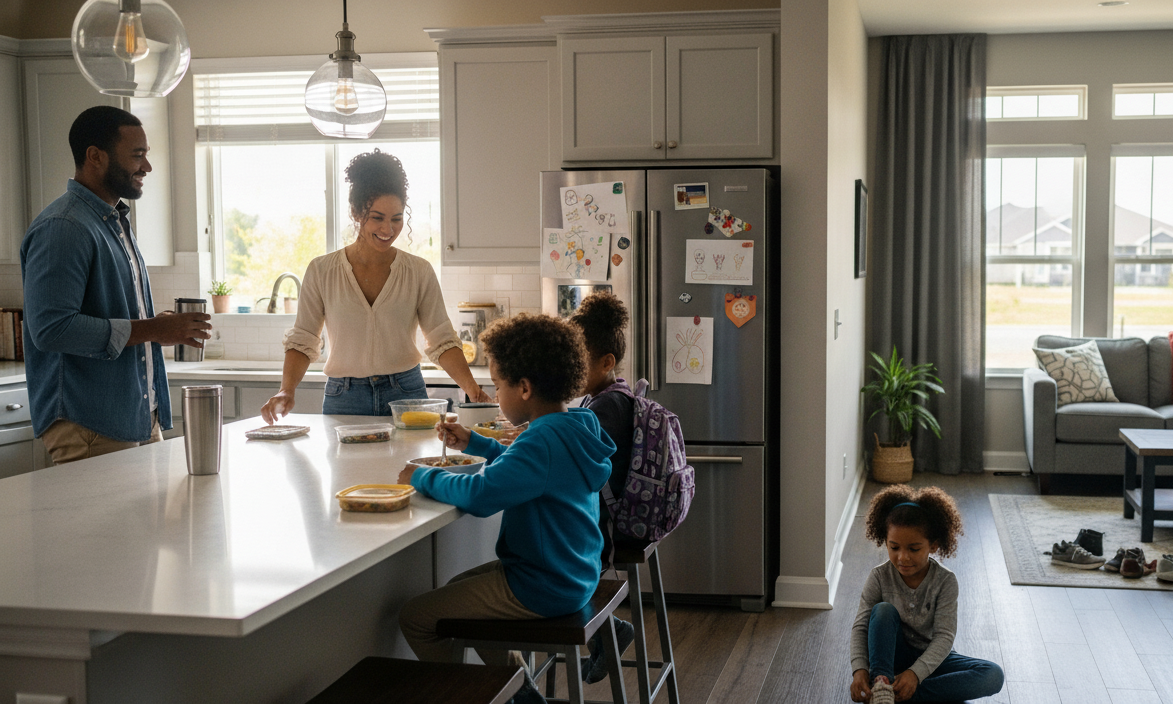
That’s where we come in. As fiduciary advisors with both CFP® and CPA credentials, we integrate tax-smart planning with real-world financial oversight. No products to push. No confusing jargon. Just data-backed advice tailored to your life.
We use our R.U.D.D.E.R.™ method to help you make better decisions, avoid costly missteps, and stay accountable to the life you actually want, not someone else’s script. Our job isn’t to impress you with acronyms. It’s to simplify, clarify, and walk beside you through every major decision, so you can move forward with confidence.
Whether you're on track for retirement depends on your savings rate, expected lifestyle, income sources, and how many working years remain. A planner can model that clearly. Most people are surprised to find they're either closer than they thought or have specific, fixable gaps. The R.U.D.D.E.R. method structures that review across six areas: resources, understanding, direction, decisions, execution, and results. A conversation with a fee-only fiduciary planner gives you an honest read, not a sales pitch.
There's no minimum asset threshold to work with Chesapeake Financial Planners. We work with professionals, business owners, and families ready for a real plan, whether that means a standalone financial plan or ongoing investment management. Financial planning and management oversight is priced at $3,000 to $10,000 per year depending on complexity. Investment management starts at 1.3% of assets and scales down to 0.35% as portfolios grow. Fees are always disclosed upfront, before any commitment.
Yes, a financial planner can help you retire early, and the earlier you start planning, the more options you have. Early retirement isn't just about hitting a savings number. It requires coordinating investments, tax strategy, healthcare coverage, and income sequencing so your money lasts as long as you need it to. The R.U.D.D.E.R. method maps that process explicitly: modeling different timelines, testing trade-offs, and stress-testing plans against real-life variables. Clients who retire in their 40s or 50s almost always point to intentional planning started years earlier, not a single lucky break.
Before hiring a financial advisor, ask whether they're a fiduciary, how they're compensated, what credentials they hold, and how they'll personalize advice to your situation. Four questions to prioritize:
1. Are you a fiduciary? A fiduciary has a legal obligation to act in your interest, not just recommend "suitable" products.
2. How are you paid? Fee-only, commission-based, and hybrid models create different incentives.
3. What credentials do you hold? Look for CFP, CPA, or ChFC designations, not just titles.
4. Will I work directly with you? Some firms hand clients off to junior staff after onboarding.
Ask these before the second meeting, not after signing an agreement.
When the market crashes, the most protective move is staying invested according to your plan rather than selling into the decline. Historically, investors who exit during downturns lock in losses and miss the recovery. Three things to do instead: review your asset allocation to confirm it still matches your timeline, rebalance if drift has left you over- or underweighted, and look for tax-loss harvesting opportunities. Jeff Judge notes that the costliest decisions most clients ever make happen in the first 72 hours of a downturn, before they've had time to think. If you're tempted to sell, that's usually a signal your allocation was too aggressive before the crash.
The most reliable way to grow wealth is to coordinate investing, tax reduction, and savings rate together, not treat each as a separate problem. Most people optimize one and ignore the other two. Four practices that consistently compound results:
1. Raise your savings rate before optimizing investments. An extra 2% saved beats a 2% return improvement at most income levels.
2. Cut tax drag with Roth conversions, tax-loss harvesting, and account location strategy.
3. Control what you can: savings rate, fee structure, and rebalancing discipline. Don't try to outguess markets.
4. Build accountability into the process. Plans that don't get reviewed don't get followed.
Jeff often sees clients gain more ground in one focused planning year than in the previous five years of uncoordinated saving.
Yes, financial advice is worth it in your 30s or 40s, particularly when income is growing faster than your ability to manage it well. This is when decisions about tax strategy, investment allocation, insurance, and equity compensation have the longest time to compound, for better or worse. Five things a planner addresses during these years that most people handle poorly on their own:
1. Tax strategy beyond basic filing: Roth conversions, deferred comp timing, and capital gains management
2. Investment decisions outside a 401(k), including taxable accounts and equity awards
3. Insurance gaps that leave income, family, or business ownership exposed
4. Saving for competing goals without derailing each other
5. Building an estate plan before it becomes urgent
Jeff finds that clients who start in their 30s or 40s typically reach their retirement targets three to five years earlier than those who wait for a triggering event.
A fiduciary advisor is legally required to act in your best interest at all times. A non-fiduciary advisor is only required to recommend products that are "suitable" for you, which is a meaningfully lower standard. The difference matters most when a commission-based product benefits the advisor more than it benefits you. A fiduciary can't make that recommendation without violating their duty. Look for advisors who hold the CFP (Certified Financial Planner) designation, who are registered investment advisers (RIAs), and who disclose their compensation structure in writing before you agree to anything. At Chesapeake Financial Planners, both advisors hold fiduciary credentials and disclose compensation fully.
Comprehensive financial planning at Chesapeake Financial Planners costs $3,000 to $10,000 per year for financial planning and management oversight, depending on the complexity of your situation. Investment management is priced separately at 1.3% of assets under management for smaller portfolios, scaling down to 0.35% as assets grow. Both fees are disclosed in writing before you commit to anything. What that covers: a full financial plan, ongoing strategy across taxes, investments, and cash flow, regular accountability meetings, and proactive adjustments as your life changes. There's no hidden product revenue and no commissions embedded in the fee structure.
Yes, financial planning helps most people reach their goals faster by replacing trial-and-error with a coordinated strategy. The gains come from three directions: fewer costly mistakes around account types, tax timing, and insurance gaps; better compounding from higher savings rates and lower fee drag; and faster execution because you've thought through the decisions before they arrive. Jeff regularly sees clients who've spent years earning well but accumulating inconsistently, and within twelve months of structured planning, they've made more tangible progress than in the prior five years. The plan doesn't do the work. It ensures the work you're doing counts.
*Advisors are only obligated to apply the fiduciary standard in advisory relationships. They are not legally obligated to apply the fiduciary standard when working in Brokerage only relationships
**Mark Rossbach is the only advisor who has attained the RICP and CPA Designations and Jeff Judge is the only advisor who has attained the CFP, ChFC and CLU Designations
Book a short “Fit Call” to see if we’re the right partner for your financial life. No pressure, no jargon, just a conversation focused on your goals and whether our approach makes sense for your needs.